What Is a Trust Fund? Complete 2026 Guide (Step-by-Step)
A trust fund is a legal arrangement where a grantor transfers assets to a trustee, who manages and distributes them to a beneficiary according to the grantor's instructions. Trust funds are used to avoid probate, reduce estate taxes, protect assets from creditors, and control how and when beneficiaries receive money or property. They aren't reserved for the wealthy — anyone with a home, savings, or life insurance policy can benefit from one.
In this guide, I'm going to walk you through everything — what a trust fund actually is, the different types of trusts you can choose from, who's involved, current 2026 tax figures, and how to set one up step by step. No jargon-heavy legalese. Just a straight, honest breakdown, the way I'd explain it to a friend over coffee.
Before you dive in, you might also want to check out our guides on wills vs. trusts and how to choose an estate planning attorney — they pair well with this one.
Let's get into it.
What Is a Trust Fund, Exactly?
A trust fund is a legal entity that holds property or assets on behalf of another person, group, or organization. It's not a bank account. It's not a will. It's its own separate legal "box" that owns things on your behalf.
Think about it this way. You put money, real estate, or investments into this box. Then you appoint someone trustworthy to manage that box. And finally, you decide who gets to benefit from what's inside.
A trust fund is also one of the most flexible tools in estate planning. You can use it to avoid probate, minimize taxes, protect assets from creditors, or simply make sure your kid doesn't blow their inheritance at 18.
Why "Trust Fund" Doesn't Mean "Rich Kid"
According to FindLaw, trust funds are used across all income levels, not just by wealthy families. In fact, most trusts drafted by estate attorneys today are for middle-class families trying to avoid probate court, not multimillion-dollar estates.
You could set one up to:
Pay for a grandchild's college education
Support a family member with special needs
Donate to a cause you believe in after you're gone
Simply skip the long, expensive probate process
None of that requires millions in the bank. It just requires a plan. If you haven't started one yet, our estate planning checklist is a good next stop.
The Three Key Roles in a Trust Fund
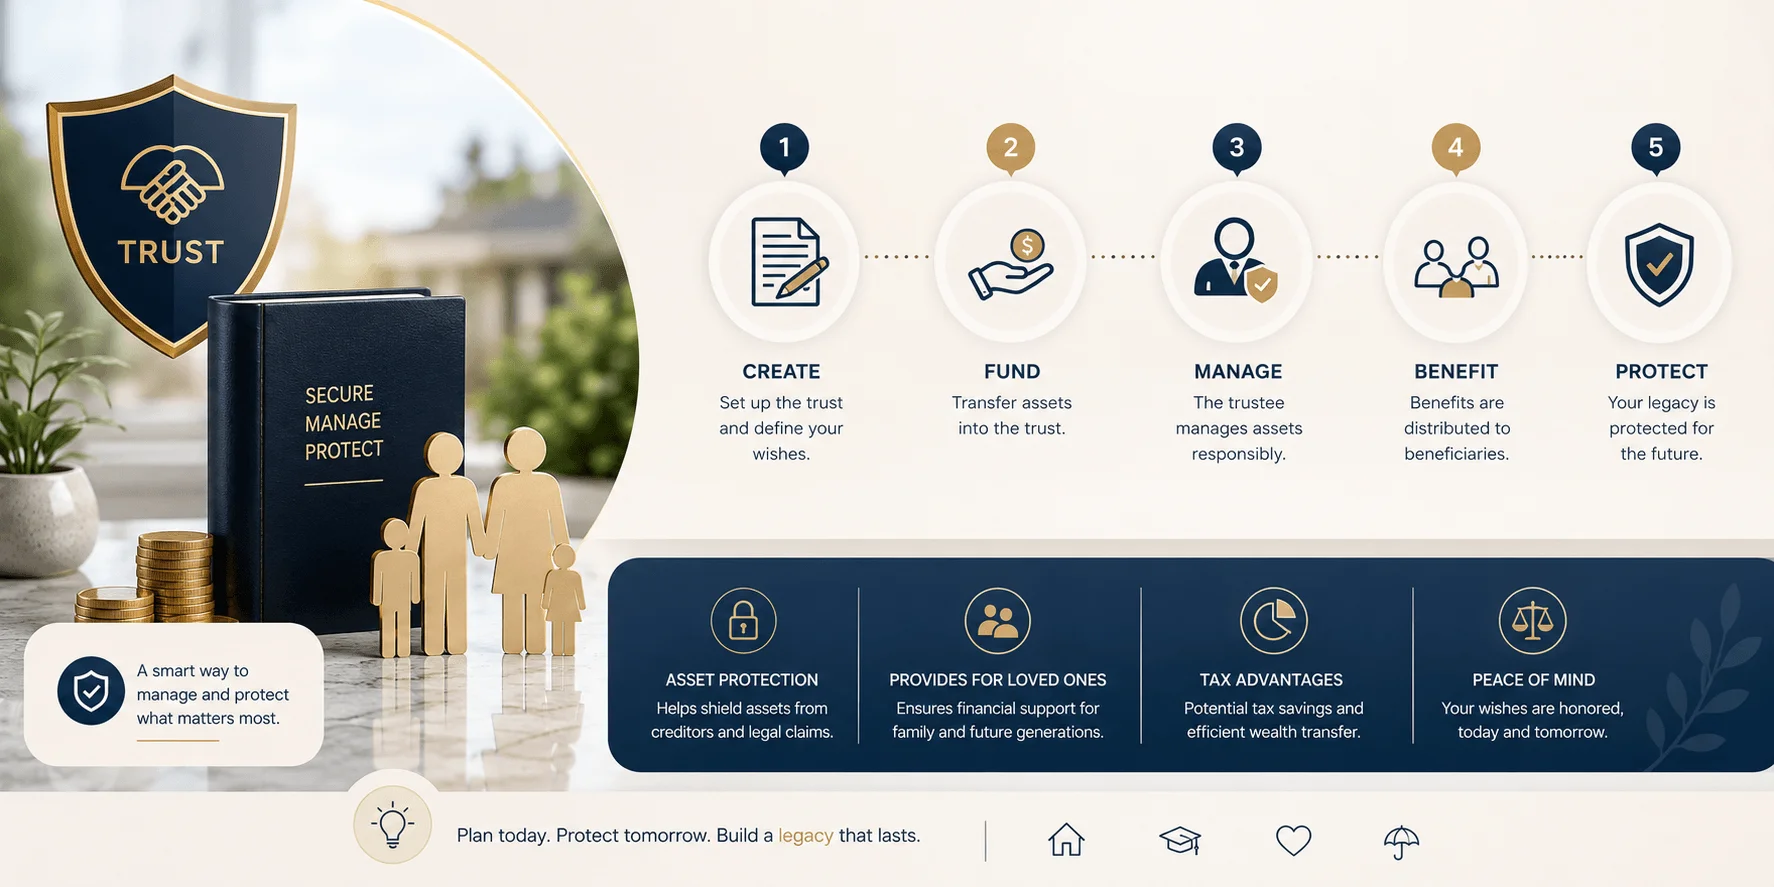
Before we go further, you need to understand the three people (or entities) involved in every trust.
1. The Grantor
The grantor — also called the settlor or trustor — is you. You're the one who creates the trust and decides which assets go into it. You also set the rules: who gets what, and when.
2. The Trustee
The trustee is the person or institution responsible for managing the trust according to your wishes. This could be a family member, a close friend, or a professional trust company. This person has a fiduciary duty to act in the beneficiaries' best interest — legally and ethically.
3. The Beneficiary
The beneficiary is whoever benefits from the trust — your kids, your spouse, a charity, anyone you name. They don't manage the assets. They just receive them, according to the terms you laid out.
Types of Trust Funds You Should Know About
Not all trusts work the same way, and picking the wrong type can cost you — in taxes, in flexibility, or in control. Here's a quick side-by-side before we break each one down.
Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
Can be changed after signing? | ✅ Yes, anytime | ❌ No, generally permanent |
Avoids probate? | ✅ Yes, if funded | ✅ Yes |
Reduces estate taxes? | ❌ No | ✅ Often, yes |
Protects assets from creditors? | ❌ Limited | ✅ Strong protection |
Who controls the assets? | You (the grantor) | The trustee |
Best for | Flexibility, probate avoidance | Tax planning, asset protection, Medicaid planning |
Revocable Trusts (Living Trusts)
A revocable trust, often called a living trust, is one you can change or cancel anytime while you're alive. This is the most common type people start with, mainly because it's flexible.
Want to add a beneficiary? Go for it. Change your trustee? No problem. Remove an asset? You can do that too.
The tradeoff is that revocable trusts don't offer much protection from creditors or estate taxes, because legally, you still "own" the assets.
Irrevocable Trusts
An irrevocable trust is basically permanent. Once it's set up, you can't easily change it. That rigidity is exactly what gives it power.
Since you no longer legally own the assets, they're removed from your taxable estate. This matters more than ever in 2026 — the federal estate tax exemption is a moving target that Congress revisits regularly, so anyone with a sizable estate should confirm the current threshold with an attorney or the IRS before assuming their estate falls under it.
Common types of irrevocable trusts include:
Irrevocable life insurance trusts (ILIT) — keeps life insurance payouts out of your estate
Special needs trusts — supports a beneficiary without disqualifying them from government benefits
Charitable remainder trusts (CRT) — pays you income now, then donates the remainder to charity
Living Trusts vs. Testamentary Trusts
Here's another distinction that confuses people: living trusts vs. testamentary trusts.
A living trust is created while you're alive. A testamentary trust is created through your will, meaning it only takes effect after you pass away, and it has to go through probate first.
If avoiding probate is your main goal, a funded living trust is usually the better route.
Which Trust Fits Your Situation? A Quick Decision Guide
Want flexibility and control while you're alive? → Revocable/living trust
Want maximum tax and creditor protection? → Irrevocable trust
Have a family member with a disability? → Special needs trust
Want to give to charity and get income now? → Charitable remainder trust
Only want the trust to activate after you die? → Testamentary trust
How Does a Trust Fund Actually Work?
Here's the general process, step by step.
Step 1: Decide Your Purpose
Ask yourself why you're doing this. Are you trying to avoid probate? Minimize taxes? Protect a vulnerable family member? Your trust purpose shapes everything else, including which type of trust makes sense.
Step 2: Choose Your Trustee
Your trustee needs to be someone reliable, financially responsible, and willing to follow your instructions to the letter. Many people choose a professional trustee or trust company for larger or more complex estates.
Step 3: Draft the Trust Agreement
This is the legal document — your trust agreement — that spells out who the beneficiaries are, what the trustee's responsibilities look like, and how and when the trust will end.
If the trust will need its own tax identification number — for example, to open a bank account or file tax returns — your attorney or trustee may need to complete a W-9 form as part of that process.
Work with an estate planning attorney here. Templates exist, but a poorly worded trust can create massive headaches for your family down the road. See our guide to choosing an estate planning attorney for what to look for.
Step 4: Fund the Trust
A mistake many people make: they create the trust, sign the paperwork, and never actually transfer assets into it. That's an unfunded trust, and it's basically useless. You have to formally retitle assets — property deeds, bank accounts, investment portfolios — into the name of the trust.
Step 5: Manage and Distribute
Once funded, the trustee manages the assets according to your instructions. When your specified conditions are met — a beneficiary turning 25, graduating college, whatever you decided — the trustee distributes the assets accordingly.
Benefits of Setting Up a Trust Fund
Avoiding probate is probably the biggest one. Probate is the court process that validates a will, and it commonly takes several months to over a year, with legal and court fees that can run into the thousands depending on estate size and state.
Beyond that, trusts offer:
Privacy — unlike a will, trusts generally aren't public record
Control — you decide exactly when and how beneficiaries receive assets
Tax efficiency — especially with irrevocable structures
Protection for vulnerable beneficiaries — minors, people with disabilities, or family members who aren't great with money
Common Mistakes People Make With Trust Funds
Not funding the trust. Creating the trust document isn't enough — you have to actually transfer ownership of assets into it.
Choosing the wrong trustee. Don't just pick your oldest child because it feels obligatory. Pick someone actually capable of handling the responsibility.
Skipping professional help. DIY trust kits exist, but for anything beyond the simplest estate, an attorney is worth the cost.
Forgetting to update it. Life changes — marriages, divorces, new kids, new assets. Your trust should evolve with you.
Frequently Asked Questions About Trust Funds
Is a trust fund only for wealthy families?
No. A trust fund is useful for anyone with assets they want managed or distributed a specific way, regardless of net worth. Many middle-class families use trusts to avoid probate or provide for minor children.
What's the difference between a trust fund and a will?
A will only takes effect after you die and typically goes through probate. A trust fund can take effect during your lifetime, often avoids probate entirely, and offers more privacy and control.
Can I be my own trustee?
Yes, with a revocable living trust, you can act as your own trustee while you're alive and name a successor trustee to take over after your death or incapacity.
How much does it cost to set up a trust fund?
Costs vary widely depending on complexity, but working with an estate planning attorney typically ranges from a few hundred to a few thousand dollars, depending on your state and the trust's complexity. Simple DIY revocable trusts can cost less, but carry higher error risk.
Do trust funds avoid all taxes?
Not automatically. Revocable trusts generally don't reduce estate taxes since you still legally own the assets. Irrevocable trusts can offer more significant tax advantages since ownership is transferred out of your estate — check current federal and state exemption thresholds, since these change periodically.
How long does it take to set up a trust?
A straightforward revocable living trust can often be drafted and signed within a few weeks, though funding the trust (transferring assets) can take longer depending on how many accounts and properties are involved.
Final Thoughts
A trust fund isn't some mysterious tool reserved for the wealthy elite — it's a practical, flexible way to protect your assets and take care of the people who matter to you. Whether you go with a revocable trust for flexibility or an irrevocable trust for stronger protection, the important thing is starting the conversation with a qualified estate planning attorney who can tailor it to your specific situation.
If you're on the fence, ask yourself this: what happens to your assets, and the people depending on you, if something happened tomorrow? That question alone is usually enough to get people moving. For next steps, check out our wills vs. trusts comparison and estate planning checklist.
Written by
Alex
Creative blogger sharing insights, stories, and fresh ideas.